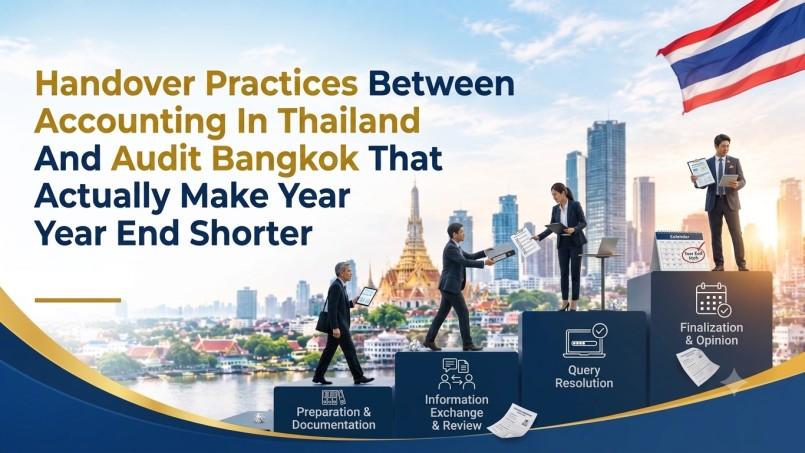
Businesses accept that year-end audit is slow. It is treated as a season the finance function endures rather than as a process that can be genuinely shortened. In practice, most year-end delay is not caused by the audit work itself. It is caused by the handover between Accounting in Thailand practice and the audit team, and the handover can be improved substantially without changing either provider. The businesses that do this see year-end shorten by weeks.
Why The Handover Is Where The Time Actually Sits
The audit itself, once fieldwork begins with clean records, is usually not the slow part. The slow parts are the reconciliations that should have been done monthly but were left to year-end, the documentation requested that has to be located rather than provided, the queries that arise because the records the auditor received differ from what was expected, and the adjustments that pile up because small errors accumulated without being caught. All of these live at the handover, not at the audit itself, and all are fixable through practice changes rather than through faster audit work.
The Handover Practices That Shorten Year-End
Monthly Reconciliation Rather Than Year-End Reconciliation
The single largest source of year-end delay is reconciliations left undone during the year. Bank reconciliations, intercompany balances, subsidiary ledgers and payroll all should reconcile monthly. When they do not, year-end starts with a reconstruction exercise that can take weeks before the audit itself even begins. Monthly reconciliation is basic discipline, and it is where accounting practice most directly determines audit speed.
Pre-Audit Query Anticipation
Strong accounting practice knows which entries the auditor will query and prepares the supporting documentation before fieldwork begins. Unusual transactions, large adjustments, related-party entries, judgemental accruals. Providing the support with the record, rather than in response to a query, removes days from the audit. Weak practice waits for the query and then locates the support, which cascades through fieldwork.
Rolling Documentation Rather Than Year-End Documentation
Employment contracts, corporate resolutions, contract renewals and other supporting documents should be filed as they arrive. When they are, the auditor can access them directly. When they are not, year-end includes a document-hunting exercise that consumes staff time on both sides. Rolling documentation is cheap to maintain and expensive to reconstruct.
Direct Auditor Access To Structured Data
Where the auditor can access the accounting system directly under agreed permissions, or receive data in structured form ready to import into audit tools, fieldwork is substantially faster than where records are exchanged as PDFs and spreadsheets. This requires a decision about how records are shared, and once made, it saves time on every audit.
What The Auditor Actually Notices
Strong Audit Bangkok practice recognises the difference immediately between businesses where these handover practices are in place and businesses where they are not. The audit engagement lead usually can tell within the first week of fieldwork whether year-end will be routine or difficult. The recognition is not a judgement about the business; it is a practical read of how the records will flow. Businesses that ask their auditor for feedback on the handover often get useful, specific advice on what to change.
Why Businesses Rarely Implement These Practices
Three reasons. First, the discipline is invisible until year-end, and by then it is too late to apply retrospectively. Second, the payoff arrives later than the work, so the accounting team feels the cost of monthly discipline without directly seeing the benefit. Third, no one is specifically accountable for handover quality; the accountant reports to finance and the auditor is engaged separately, and neither party owns the discipline in between. Naming the accountability changes what gets done.
How To Make This Change This Year
The practical steps are straightforward. Identify the three or four reconciliations most often left to year-end and move them to monthly. Ask the auditor which queries recur every year and prepare documentation for those in advance. Adopt a rolling documentation habit rather than a year-end scramble. Discuss with the auditor whether direct access to structured data is feasible for the next engagement. None of these requires additional headcount or new systems; each requires deliberate practice change. Employers who invest in coordinated Accounting in Thailand support with these disciplines built in find year-end shortens noticeably within one audit cycle.
Frequently Asked Questions
Why is the handover the source of year-end delay rather than the audit itself?
Because the audit, once fieldwork begins with clean records, is usually not the slow part. The slow parts are the reconciliations, documentation location, unexpected queries and accumulated adjustments that all live at the handover.
What are the specific handover practices that shorten year-end?
Monthly reconciliation, pre-audit query anticipation, rolling documentation, and direct auditor access to structured data. All are practice changes rather than resource changes.
What does strong audit practice actually notice about the handover?
Auditors can usually tell within the first week of fieldwork whether year-end will be routine or difficult. The recognition is a practical read of how the records flow, not a judgement about the business.
Why do businesses rarely implement these practices?
Because the discipline is invisible until year-end, the payoff arrives later than the work, and no one specifically owns handover quality. Naming the accountability changes what gets done.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek